 Analysis by Appwee
I judge a budgeting app less by how many charts it can show me and more by whether it changes what I do before I spend. You Need a Budget—usually shortened to YNAB—puts that decision at the center: instead of waiting until the end of the month to see where money went, I plan where the money I have should go. That makes it a distinctive kind of finance app, and it can be genuinely useful if you want to make deliberate choices rather than just watch balances move.
The approach also sets a clear expectation: budgeting here is an active habit, not a one-time setup. I have to look at the plan, record or review spending, and adjust when real life differs from what I expected. For someone who wants that involvement, the routine can turn vague intentions into concrete choices. For someone who only wants a passive snapshot of accounts, it may feel like more work than necessary.
A budget built around the money already available
The central idea is to assign available money to purposes before spending it. I might set aside part of what I have for housing, food, transport, and a future bill, then make choices with the remaining amounts in view. That is different from treating a monthly income estimate as permission to spend money that has not arrived yet. The practical benefit is clarity: I can see what a purchase competes with, rather than relying on a rough sense that there should be enough left.
This method is especially helpful when income or expenses feel hard to coordinate. A bill that comes due occasionally can be easier to handle when I give it a place in the plan ahead of time, instead of letting it appear as a surprise. It does not make an expensive bill disappear; it makes the trade-off visible earlier, when I still have choices about where to put the money.
What the routine looks like in practice
For me, the useful habit is a brief check-in: look at the money available, decide what needs attention, and adjust categories when priorities change. If groceries cost more than I planned, I can move money from a less urgent category instead of pretending the original plan still fits. That small act matters. A budget that can be revised is more realistic than one that treats every estimate as a rule I have failed the moment circumstances change.
Imports can help reduce manual entry, but I would not treat them as a substitute for reviewing activity. A transaction may arrive later than a purchase, and a quick check after spending helps keep the plan meaningful. If an amount is assigned to the wrong category or a purchase has not appeared yet, the balance I rely on could be misleading. My practical tip is to check recent activity during the same budgeting routine rather than waiting until the end of the month to reconcile everything.
That makes the app a better fit for people willing to stay engaged than for those expecting a budget to maintain itself. I would also keep the first setup modest: start with the categories that match real priorities, then add detail when it answers a question I actually have. An elaborate plan can look impressive but become a chore to maintain. The point is not to classify every purchase perfectly; it is to make the next decision with enough context.
More From Our Writers

OTR Makes Off-Road Roaming a Perfect Fit for Short Play Sessions

Prime Video vs. Netflix and Disney+: More Choice, More Clutter

SHAREit Review: A Fast, No-Cloud Way to Move Files

Cryptoguru Makes Crypto Trading Safer, but Can It Teach Restraint?

FC Mobile 26 Turns Soccer into a Season-Long Service

Reddit Is Worth Your Time Only If You Choose Your Communities
Using YNAB as an everyday money tool
YNAB is a finance app from ynab.com. It is free to install, rated for Everyone, and its current version is 26.6.1, with iOS 11 as the minimum operating-system requirement. It has a 4.5 average from around 24,000 ratings and more than 1 million installs. The app includes in-app purchases, with items ranging from $14.99 to $109.00, so I would check the current offer and terms before committing. Those details matter because a budgeting routine only helps if the ongoing cost makes sense for your situation.
When the plan earns its place
A realistic example is a week when a routine grocery shop runs higher than expected, while a utility bill is due soon. In a simple spending tracker, I might notice both events but still have to work out what they mean for the rest of the month. With a category-based plan, I can check what has already been reserved, decide whether to move money from a lower-priority purpose, and make that choice before another purchase. The app does not choose for me; its value is making the consequences easier to see.
This is where goal planning can be more than a motivating graphic. A larger target becomes easier to act on when I treat it as a purpose competing for money alongside current needs. I would start with a manageable contribution and revisit it when circumstances change, rather than setting an ambitious target that leaves everyday categories unrealistic. A goal is useful when it guides a decision, not when it simply looks encouraging on a screen.
Shared budgeting can benefit from the same visibility. If two people are working from one plan, checking it before a discretionary purchase can prevent the familiar “I thought we had room for that” conversation. The important habit is agreeing on what the categories mean and when to update spending. A shared view cannot resolve different priorities by itself, but it gives both people a common place to discuss them.
How it compares with simpler alternatives
Many banking apps and expense trackers are designed mainly to show balances, list transactions, or group past spending. That can be enough if my goal is to monitor activity with as little effort as possible. YNAB asks for a different kind of attention: I decide what available money is for, then use those assignments to guide later choices. I find that more actionable than a retrospective report, but it is not automatically better for everyone. Someone who already has a comfortable system and only wants a quick account overview may prefer the lighter approach.
A spreadsheet can offer more freedom to design categories and formulas, and it may suit someone who enjoys maintaining a personal system. The trade-off is that I have to build and preserve that structure myself. YNAB provides a focused budgeting workflow instead, but I still need to use it consistently. If I want complete control over a custom spreadsheet, or do not want to pay for a service after considering its purchase options, a spreadsheet or a free tracker may be the more sensible choice.
Where the extra effort can become friction
The biggest drawback is not that the method is complicated; it is that it requires repeated attention. When I am busy, it is easy to postpone categorizing or reviewing transactions, and then the budget becomes less trustworthy. I would avoid relying on an old category balance for a decision if I have not checked recent spending. A short, regular review is more useful than an occasional marathon cleanup, but anyone who does not want that responsibility may find a passive tracker easier to live with.
There is also a learning curve in changing from “What did I spend?” to “What should this money do now?” At first, deciding how much to assign to each purpose can feel artificial, especially if expenses vary. I would treat early allocations as working estimates rather than promises. When a category repeatedly needs adjustment, that is information about how I actually spend, not proof that I have failed at budgeting.
Connected transaction imports can save typing, yet I would still check that the activity is current and categorized sensibly. A budget is only as useful as the picture I am using to make choices. If I prefer to enter every purchase manually, I can make that part of the routine; if I rely on imports, I should still review them instead of assuming that an account connection removes all need for attention.
The app’s free installation should not be confused with a no-cost budgeting service. The in-app purchase range is broad, so the sensible next step is to inspect the offer shown in the app and decide whether the cost fits the value I expect to get. That matters most for someone who is still unsure whether they will keep up the habit. I would first decide whether the method itself suits me, then weigh the purchase against how regularly I expect to use it.
Who is likely to benefit most
I would recommend trying this approach to someone who gets paid, pays bills, and still feels uncertain about what is safe to spend. It can also suit a person who is saving toward a specific expense or trying to make debt payments part of a broader plan, provided they are ready to review and adjust categories. The benefit is not that every month becomes predictable. It is that changes can be handled as decisions rather than discovered only after money is gone.
I would steer away from it if I wanted an app that quietly tracks everything without requiring regular input, or if I only needed a basic list of recent transactions. It may also be a poor match if subscription spending is a concern and I would not use a structured budget often enough to justify the cost. In those cases, a bank’s built-in overview, a simpler expense tracker, or a spreadsheet may be a better fit.
YNAB is developed by ynab.com, and it has been available since October 20, 2015. The large audience—around 4,600 written reviews alongside its ratings—suggests that this is an established budgeting option, though popularity alone cannot tell me whether its hands-on method will suit my habits. I would judge it by whether assigning money ahead of time helps me make calmer, more informed choices.
My take after weighing the trade-offs
If you've ever found yourself overwhelmed by budgeting, You Need a Budget (or YNAB for short) might just be your financial savior. I’ve been using it for a while now, and let me tell you, it’s like having a personal financial advisor right in your pocket. In this review, I’ll walk you through what makes YNAB stand out, how it works, and why it might be the budgeting tool you’ve been searching for.
First things first, setting up YNAB is straightforward. The app is available on both Android and iOS, so no matter your device preference, you’re covered. Once downloaded, YNAB guides you through the initial setup process with a series of prompts that make it easy to link your bank accounts and start tracking your finances. The interface is super intuitive, which is a big plus if you’re like me and want to avoid any unnecessary tech headaches.
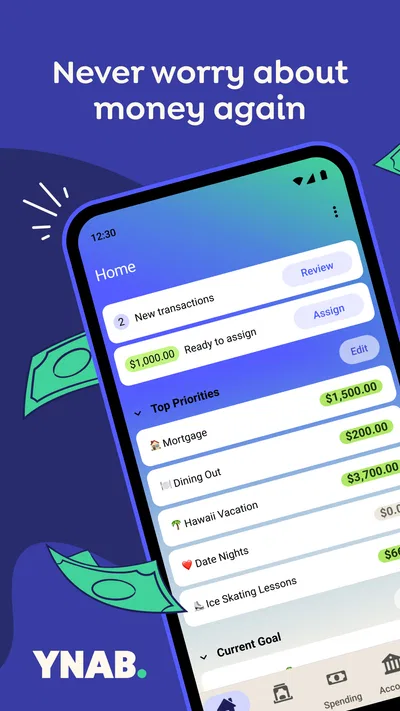
What I love about YNAB is its focus on giving every dollar a job. This means you allocate your money to specific categories—like rent, groceries, entertainment—before you even spend it. It’s a proactive approach that helps you stay on top of your finances and avoid those dreaded end-of-month surprises.
Features That Make YNAB Stand Out
One of the standout features of YNAB is its ability to sync across devices. Whether you’re updating your budget on your phone or your laptop, it’s all seamless. Plus, the app’s real-time updates ensure that both you and your partner (if you’re budgeting together) are always on the same page.
Another feature worth mentioning is the goal-setting tool. You can set short-term and long-term financial goals, and YNAB will help you track your progress. Whether it’s saving for a vacation or paying off debt, having a visual representation of your goals can be incredibly motivating.
YNAB also offers a plethora of educational resources. From live workshops to a lively community forum, you’re never short of advice and support from fellow budgeters. I personally found their workshops incredibly helpful when I was just starting out.
Daily Use and Experience
Using YNAB daily has become a routine for me. The app’s design is clean and user-friendly, making it easy to check in on my budget whenever I need to. I particularly enjoy the transaction import feature, which automatically pulls in my spending data. It saves me a ton of time and helps ensure that my budget is always up to date.
One thing to note is that YNAB operates on a subscription model. While some might hesitate at the idea of paying for a budgeting app, I personally find it worth the investment. The insights and control YNAB provides over my finances have more than justified the cost.
Why YNAB Could Be Your Next Budgeting Tool
If you’re serious about taking control of your finances, YNAB offers a comprehensive solution. Its proactive budgeting approach, combined with robust features and community support, make it a standout choice. Whether you’re a seasoned budgeter or just starting out, YNAB offers tools that cater to all levels of financial literacy.
In the end, the choice comes down to what you need from a budgeting app. If transparency, ease of use, and financial education are high on your list, YNAB is definitely worth a try. With a free trial available, there’s really nothing to lose, but potentially a lot to gain.
So, are you ready to give every dollar a job and transform your financial future? With YNAB, you might just find budgeting to be less of a chore and more of an empowering journey.
YNAB Pros and Cons
- Intuitive budget tracking interface.
- Real-time financial updates.
- Syncs across all devices seamlessly.
- Strong community support and resources.
- Customizable categories for expenses.
- Requires subscription after free trial.
- Steep learning curve for beginners.
- Limited investment tracking features.
- No built-in bill payment option.
- Internet required for full functionality.
YNAB Frequently Asked Questions
What is YNAB and how does it work?
YNAB, short for 'You Need a Budget', is a personal finance app designed to help users manage their money by following a proactive budgeting approach. It allows users to allocate every dollar they earn to specific categories, ensuring that they spend only what they have. This method helps users stay on track with their financial goals by promoting awareness and discipline.
Is YNAB suitable for beginners in budgeting?
Yes, YNAB is highly suitable for beginners. The app offers a user-friendly interface along with educational resources, including tutorials and workshops, to guide new users through the budgeting process. The app’s emphasis on simplicity and clarity makes it easy for beginners to understand their finances and start budgeting effectively.
Does YNAB support syncing with multiple devices?
Yes, YNAB supports syncing across multiple devices. Whether you are using a smartphone, tablet, or desktop, your data is consistently updated in real-time. This feature ensures that users can access and manage their budgets seamlessly from anywhere, making it convenient to track expenses on the go.
What are the main benefits of using YNAB over other budgeting apps?
YNAB stands out due to its unique budgeting philosophy, which focuses on proactive money management and goal setting. Unlike many other apps, YNAB encourages users to plan ahead by assigning every dollar a job. This method not only aids in better financial control but also helps users build savings and reduce debt more effectively.
Is there a subscription fee for using YNAB?
Yes, YNAB operates on a subscription model. While it offers a free trial period, continued use requires a paid subscription. This fee supports ongoing updates and customer support, ensuring users have access to the latest features and assistance. Many users find the investment worthwhile due to the financial benefits and insights YNAB provides.
Gallery